- Baris Kalay
- APAC Corporate Sales Head, Global Payments Solutions, Bank of America
- Phil Carmalt
- Head of APAC Treasury Product, Global Payments Solutions, Bank of America
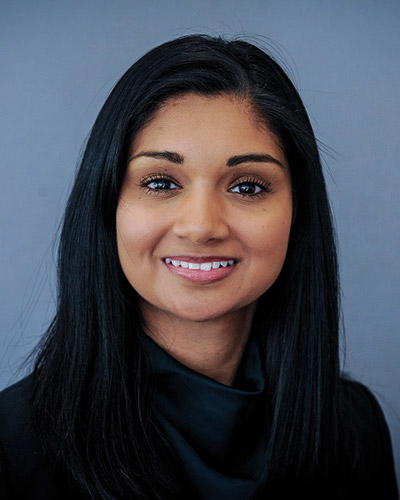
- Serina Hourican
- APAC Global Commercial Sales Head, Global Payments Solutions, Bank of America
- Tom Alford
- Deputy Editor, Treasury Management International
Transactional FX Options Making Treasury Life Easier in APAC
APAC’s trading vibrancy is sometimes tested by cross-border payment inefficiencies. Bank of America’s Serina Hourican, APAC Global Commercial Sales Head, Phil Carmalt, APAC Product Head, and Baris Kalay, APAC Corporate Sales Head, examine the challenges and the transactional FX options available to lock certainty, accelerate cash, and reduce operating costs.
The expectation that cross-border payments should operate flawlessly is a reasonable one, but it remains unfulfilled for many APAC treasurers. Fragmented infrastructures — including ongoing reliance on correspondent banking networks — continue to create friction across the region, notes Hourican.
These challenges are often compounded by limited payment transparency, even where tracking solutions exist. Once currency conversion is added to the mix, the result is greater complexity and higher costs.
Significant progress has been made in recent years, particularly through the rollout of real-time domestic payment systems such as PayNow in Singapore, DuitNow in Malaysia, and Hong Kong’s Faster Payment System (FPS). However, while these platforms function effectively within national borders, their advantages have been slower to translate into seamless cross-border flows.
For large multinational corporates operating across APAC — often with frequent and high-value transactions — Kalay highlights the cumulative impact of local currencies, regulatory regimes, and operational standards. Each additional market, he says, “is a potential source of friction”.
Addressing this friction remains core to the treasury mandate. For treasurers, Kalay adds, the ability to remove barriers and improve efficiency and cost control “is still at the heart of what they do, both from an operational management and cross-border payments perspective”.
Yet the regulatory reality in many Asian markets remains challenging. Highly regulated environments, combined with ongoing dependence on physical documentation — particularly for FX transactions — mean treasurers must continually balance efficiency ambitions against practical constraints. As Carmalt observes, the challenge in APAC “is always about how to become more efficient and effective with limited resources and limited IT budget”.
Against this backdrop, Bank of America continues to invest in product innovation. One recent example is the rollout of the FX Receivables online portal for India, designed to simplify cross-border collections. For each inbound FX transaction, clients are prompted to provide the ‘purpose of payment’ and ‘disposal instructions’ (the accounts to be credited in multiple currencies). Clients can also choose to upload supporting documents through the portal, reducing manual processing and delays to crediting accounts. While relatively simple in design, the solution can meaningfully accelerate cash flows, streamline reconciliation, and improve FX risk management.
Local payments, international business
“Receiving payments seamlessly in local currencies brings several important advantages, including the ability to price directly in local markets,” Kalay explains. When companies invoice and collect locally, they reduce FX costs and exposure to currency volatility. “It’s a simple but powerful benefit that helps protect margins — something especially valuable in today’s environment.”
Local currency capability can also strengthen supplier relationships. Hourican notes that many suppliers prefer local currency payments because receipts are immediately clear and predictable. “This can become a strong bargaining tool in terms of visibility over working capital, even providing some pricing flexibility.”
Another option for increasing certainty and visibility is Bank of America’s Guaranteed FX tool, available through the CashPro platform. The solution allows clients to lock in FX rates for up to one year — depending on currency pairing — reducing exposure to market volatility. It can also serve as a source of local currency for clients that might otherwise struggle to access it. Acting as a practical alternative to traditional hedging, Guaranteed FX creates greater rate stability while supporting smoother cross-border execution.
Carmalt also highlights opportunities in low-value cross-border payments, where — subject to regulatory permissions — domestic payment rails can be used for the “last mile”. However, some markets and payment types do not allow overseas originators to make “one leg out” payments, so customers should get advice from their banking partners to understand the market nuances.
For corporates paying exclusively in major trade currencies such as the US dollar, this may appear less relevant. But for lower-value flows — including salaries, pensions, or small-merchant e-commerce payments — recipients may strongly prefer local currency. This flexibility can support market expansion and deepen relationships in existing territories.
While low-value payments may be routed via domestic Automated Clearing House (ACH) systems, Carmalt acknowledges that originators are often reluctant to open non-resident accounts or manage multiple currency balances solely to access cheaper rails.
“In practice, many corporates prefer to operate a limited number of functional currencies, or even just their home currency. As market infrastructure evolves, industry participants are preparing for cross-border real-time payment options that use RTP networks to simplify these flows and potentially lower transaction costs.”
APAC continues to lead cross-border real-time payment innovation, largely through bilateral links such as Hong Kong–Thailand, Singapore–Thailand, and Singapore–India. While these corridors currently focus on C2C and some C2B flows, broader B2B adoption is expected as multilateral infrastructure develops.
Carmalt highlights Project Nexus — a multilateral initiative connecting multiple real-time payment systems in Asia — which is expected to go live in 2027. The aim is to deliver scalable, cost-effective, and accessible cross-border RTPs.
However, it’s not always necessary to wait for market infrastructure to interlink RTP networks. Bank of America is combining its internal network with trusted third-party partners — particularly for last-mile clearing — in preparation to roll out cross-border real-time payment solutions for banks, and later for non-bank FIs and Corporates.
At the same time, regulatory scrutiny continues to intensify. Carmalt notes that evolving anti‑money laundering (AML) and counter‑terrorist financing (CTF) regulations place increased emphasis on transparency, including identification of the true originator, in cross-border payments. “It will be important for corporates to ensure that the solutions they implement are both future-proof and regulatory compliant,” he warns.
Transactional FX as a strategy
“Enhancing flow efficiency, flexibility, and visibility is one of the key advantages of transactional FX,” Kalay notes. Greater use of transactional FX to send and receive payments in local currencies can materially improve forecasting and reconciliation — particularly in markets where solutions such as FX Receivables for India reduce or eliminate paper-based workflows. Beyond operational gains and lower processing costs, these tools also enrich treasury data, strengthening treasury’s strategic contribution.
Treasury’s centralised position allows it to extend these benefits across the wider organisation. Hourican explains: “Other business units and functions within the organisation may have a range of exposures in certain currencies; treasury can collate related data and review it from a netting perspective.” From that position of clarity, treasury can advise on when, where, and how FX risk should be settled — and may even centralise FX activity to become “a more cost-effective or even profitable centre.”
At a broader level, transactional FX can actively enable business growth. Carmalt argues that treasury-led FX strategies help businesses access new customer segments by facilitating local-currency payments and supporting procurement through supplier payments in preferred currencies — strengthening negotiations and reducing overall costs.
Central to success
While expanding into new currencies and markets can appear to add complexity, Carmalt believes the right banking partner and digital solutions help mitigate risk while elevating treasury’s strategic role.
Application Programming Interface (APIs) are increasingly important in this shift. Online businesses, for example, must present accurate FX rates at the point of payment. Without access to near real-time market rates, firms risk pricing errors. Bank of America’s FX APIs help resolve this challenge by refreshing prices dynamically and at scale.
These capabilities are also supporting the growing adoption of Global Capability Centres (GCCs) across APAC. GCCs typically centralise financial operations — spanning cash, liquidity, risk, and Financial Planning & Analysis (FP&A) — and increasingly apply automation and AI-driven analytics. As Kalay notes, these centres are evolving “from pure service providers towards being strategic influencers,” with growing investment driving increased billing and payment flows between APAC and headquarters.
While billing often occurs in functional currencies, GCCs frequently make payments locally. This, Kalay adds, “further highlights the importance of the intelligent use of transactional FX.”
With their expanded data access and API connectivity, GCCs are also well positioned to support real-time cash reporting, liquidity monitoring, and risk analytics. Carmalt notes that this transparency allows treasurers at HQ to make faster — and more informed — decisions.
However, many organisations have yet to adopt proactive GCC models. Cash fragmentation across entities and geographies continues to limit visibility and heighten liquidity risk. Static forecasting can force unnecessary FX conversions or overly frequent cash sweeps. “But by holding balances in FX accounts armed with the right tools,” Kalay explains, “treasurers can avoid these challenges, executing FX conversions only when truly required.”
Trending now
Managing a growing number of currency positions need not create additional risk if the right solutions are in place. Carmalt points to multicurrency notional pooling, which is increasingly used across markets such as Hong Kong, Singapore, Australia, and Japan. By offsetting long and short positions across entities, treasurers can optimise FX conversions or reduce borrowing costs while maintaining operational continuity — even where accounts temporarily move into debit positions.
AI is also becoming increasingly relevant to transactional FX. While treasurers explore a mix of in-house and vendor-led AI solutions, many are turning to trusted banking partners to incorporate AI safely and effectively. Bank of America’s CashPro Forecasting tool, for example, uses AI to continuously refine forecasting accuracy — enabling more timely and informed FX risk decisions.
AI also underpins advanced fraud and anomaly detection. Beyond traditional payment monitoring, transactions outside established behavioural patterns — such as new beneficiaries or currencies — are subject to continuous AI learning. This reduces false positives while enhancing detection of emerging threats, including increasingly sophisticated deep fake fraud.
More positively, AI is improving servicing experiences. “Bank of America’s CashPro Chat is able to answer client questions in an ever more human-like manner,” Carmalt notes.
Visibility adds control
“For treasurers, creating more integrated FX workflows across business units and uncovering new ways to centralise and standardise data has become mission-critical,” Hourican says. “As the industry evolves, the next few years will demand far greater visibility and control over transactional FX — empowering companies to break through today’s cross-border frictions and unlock faster, more predictable payment outcomes across APAC.
“And with the rise of next-generation digital currency innovations — such as programmable money, tokenised deposits, and CBDCs pilots — we will see entirely new layers of transparency, settlement speed, and risk reduction emerge. These advancements have the potential to fundamentally reengineer cross-border commerce, making global payments simpler, smarter, and more inclusive. In this environment, those who modernise FX at the flow level will gain greater certainty, visibility, and control; those who don’t will find friction increasingly expensive.”